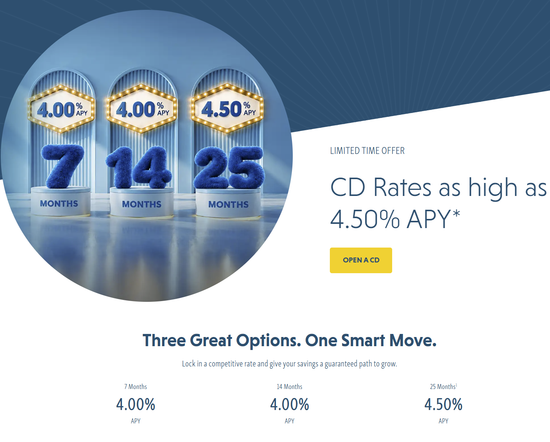
New Climb Credit Union CD Rates
I don’t normally go chasing CD rates all over town, but I happened to stumble across a webpage / ad that had these on it. Typically, credit unions offer “special” rates as a way to compete with other institutions and interest bearing accounts without having to increase their cost of deposits as much by paying everyone higher rates.
These odd-terms are the secret sauce. A 7-month CD renews as a standard term, and standard interest rate 6-month CD. And, of course, current CD account holders will find their 6-month CDs and 12-month CDs rolled over to their corresponding base CD rates of 3.80% and 3.70% respectively. Essentially, the set-it-and-forget types who don’t pay attention to their money or what it is doing will earn the lower rates. Otherwise such specials put the credit union out of balance with income and expenses.
Notice also the fine print on that 4.50% for 25 months CD. Follow that tiny 1 to the bottom of the page and you’ll see that the 4.50% rate only applies to “new money,” as in money that is not already on deposit at the credit union.
Rates like that are designed to bring in funds, not to make the funds already on deposit more expensive. Members tend not to be super happy about the distinction, but it does matter, and since credit unions are not-for-profit organizations, higher expenses in one place have to be offset somewhere else in the form of higher fees, or higher loan rates.
Either way, if you have an account at Climb and have some money laying around that you want to lock up at 4.50% for a while, that’s an option. Otherwise, that 4.0% is a solid enough rate to not bother looking around.
Do keep in mind the Fed will likely raise rates in December, so you might have other options soon enough.